Mortgage Solutions · Alberta
Buying Your Next Home in Alberta: Sell First, Buy First, and How to Move Without the Chaos
You've done this before, which is exactly why this time is trickier. There's a house to sell, a mortgage with a rate you may want to keep, equity that needs to become a down payment, and two closing dates that would very much like to line up. We do the timing, the math and the lender part. You pick the house.
The second move is a different sport. First-time buyers have one question: "how much house can I get?" Move-up buyers have six, and they're all tangled together. Do I sell first or buy first? Where does the down payment come from before my sale closes? Can I keep my rate? What's the penalty if I can't? Can I carry two mortgages for a month? And who's going to make sure the movers, the lawyer and both closing dates land in the right order?
The good news: every one of those questions has a clean answer once you know your numbers, and we can get you those numbers in a 15-minute phone call. The better news: most of the stress people feel at this stage comes from doing the steps in the wrong order, not from anything actually going wrong. Below is the order that works.
Buying your first place? You want the first-time buyer page: programs, minimum down payment, the whole game plan. This page is for people who already have keys and want a different set.
Sell First or Buy First?
Every move-up buyer hits this fork, and there's no universally right answer. There's only the right answer for your market, your money and your tolerance for living out of boxes. Here are the three paths and what each one really costs.
Sell First
You list, you sell, you know your exact equity, then you shop. This is the calm path: no bridge loan, no carrying two mortgages, and your offer on the next place is as strong as a first-time buyer's because it has no "subject to sale" condition attached.
• The upside: certainty. You know your down payment to the dollar and you never own two homes at once.
• The catch: you might sell before you've found the next place. Long possession dates (60–90 days), a short rent-back from your buyer, or a month at a family member's are how people solve it.
• Best when: the market you're selling into is slow or balanced, or your budget genuinely depends on what the house fetches.
Buy First
You find the home, you buy it, then you sell the old one. Nobody moves twice and you never lose the house you love to a buyer with no conditions. It costs more in stress and, usually, a little in interest.
• The upside: you move once, straight across, on your timeline.
• The catch: until your sale is firm, lenders may need you to qualify carrying both mortgages. Once it is firm, a bridge loan covers the gap between the two closing dates.
• Best when: the market you're selling into is hot, your income comfortably carries both payments for a short stretch, and you have a firm sale (or a very confident realtor).
Line Them Up
The middle path, and the one most of our clients land on: sell and buy at the same time with closing dates a few days or weeks apart, and bridge financing covering the overlap. It takes a little choreography. That's the part we do.
• How it works: your sale goes firm, you write on the next home with a closing shortly after (or before) your sale closes, and a bridge loan floats your down payment for the days in between.
• What we do: get you approved two ways up front, with and without the sale, so you know exactly which offers you can write and how firm you can be.
• Best when: you want to move once, keep a strong offer, and you'd rather the paperwork be our problem.
Not sure which path is yours? The four-question helper just below gives you a straight answer and a list of what to line up.
Where the Down Payment Comes From
Your down payment is probably sitting in the walls of the house you live in. Getting it out at the right moment is the whole trick. Here are the ways move-up buyers fund the next purchase, from simplest to most creative.
Sale Proceeds
The classic. Your current home sells, the lawyer pays off your mortgage, the penalty (if any) and the realtor, and what's left lands in your account as your down payment. If your sale closes before your purchase, that's it, you're done.
• Rough equity math: sale price, minus what you owe, minus commission, legal fees (usually $1,000–$1,500 in Alberta) and any mortgage penalty.
• Alberta bonus: no land transfer tax on the purchase side. Land Titles registration fees are a few hundred dollars, not a few thousand.
Bridge Financing
Your purchase closes before your sale does, and a short-term loan covers the down payment until the sale money arrives. It's interest-only, usually for a few days to a few weeks, and it's paid out automatically from your sale proceeds.
• What lenders need: a firm sale on your current home (conditions waived) and a firm purchase. Bridge loans don't work on a house that's merely listed.
• What it costs: interest at roughly prime plus a few percent, charged only for the days you use it, plus a modest admin fee. On a $100,000 bridge for two weeks, think hundreds, not thousands.
• How long: most lenders allow up to 90 days; a few stretch longer. Read Bridge Financing 101 for the full walk-through.
HELOC on Your Current Home
If you already have a home equity line of credit, you can draw on it for the down payment before you sell and repay it from the proceeds. If you don't have one, setting one up takes weeks, so this is a "plan ahead" move, not a "week before closing" move.
• The limit: the revolving portion is capped at 65% of your home's value, and all borrowing against the home can't pass 80%.
• Qualifying: the lender on your new mortgage counts the HELOC payment as a debt until it's repaid, so we plan for that.
Savings, Gifts and Investments
Plenty of move-up buyers top up with cash, an RRSP or a family gift so the sale proceeds aren't doing all the work. Gifts from immediate family need a signed gift letter; anything else needs a 90-day paper trail.
The 20% Question
Your equity from a first home often gets you past 20% down on the next one, which means no mortgage default insurance premium and access to 30-year amortizations. But insured mortgages (under 20% down) carry the sharpest rates in the market, so on some files putting down less and keeping cash aside is the smarter play. We'll show you both. It's not always the answer you'd guess.
Your Current Mortgage: Port It, Break It, or Blend It
Your existing mortgage has a rate, a term and a penalty attached to it. What you do with it on moving day can be worth thousands either way, so it's the first thing we look at.
Port It
Porting means picking up your current mortgage, rate, term, remaining amortization and all, and setting it down on your new home. No penalty. If your rate is better than what's on offer today, this is usually the winning move.
• The window: most lenders give you 30 to 120 days between your sale closing and your purchase closing to port. Miss it and the penalty applies.
• You still qualify: a port is a new approval on the new property. Same income and credit review as any purchase.
• Variable rates: most variable-rate mortgages can't be ported as-is; you typically convert to a fixed first. We'll tell you what your lender allows before you list.
• Read more: Porting your mortgage, and when it beats paying the penalty.
Blend It
Moving up usually means borrowing more. When you port and need extra money, the lender blends your old rate with today's rate on the new portion, weighted by the amounts, into one new rate. You keep the benefit of your old rate on the balance you already had.
• Blend and extend: the blended rate is stretched over a fresh full term.
• Blend to term: the blended rate runs only to your original maturity date, then you renew.
• The honest part: the new-money portion is priced off the lender's rate for that product, which is rarely their sharpest. We compare it against breaking and starting fresh elsewhere.
Break It
Sometimes the best move is to pay the penalty, close out the old mortgage and start clean with the lender and product that actually fits the next ten years of your life. This wins more often than people expect, especially when your current rate is above today's market or your lender's port rules are restrictive.
• Variable rate: the penalty is almost always three months' interest. On a $350,000 balance at 5%, roughly $4,400.
• Fixed rate: the greater of three months' interest or the Interest Rate Differential (IRD). Big banks calculate IRD off posted rates, which can push it into five figures; many monoline lenders calculate it more gently.
• Near renewal? If your maturity is within a few months, timing your closing to it can make the penalty disappear entirely.
The estimator below gives you a rough penalty and a rough blended rate on your own numbers. For the real figures, your lender's payout statement is the only source that counts, and we'll request it for you. Our penalty calculator digs deeper if you like digging.
Buying a Different Kind of Home
Your next home probably isn't a carbon copy of your first. A different type of property means a slightly different mortgage, and it's better to know the wrinkles before you write the offer.
Condo or Townhouse
Lenders add a portion of the condo fee (typically half) to your monthly debts when qualifying, so a $400 fee can trim your purchasing power. The lender will also want to see the condo's documents: reserve fund study, minutes, budget, insurance. A healthy reserve fund is a good sign for you and for them.
Acreage or Rural
Lenders value the house plus a limited number of acres, not the whole quarter-section, and outbuildings rarely count. Wells, septic systems and road access get inspected, and some lenders want a bigger down payment on rural property. The right lender matters more here than almost anywhere. Buying an acreage in Alberta covers the details.
New Build
Builder deposits, a long closing (sometimes a year or more), and a rate hold that needs to survive it. Some lenders offer extended holds specifically for new construction. GST applies to new homes (with a partial rebate under certain price thresholds), and you'll want your own lawyer, not the builder's. If you're building rather than buying from a builder, a construction mortgage with staged draws is the tool; ask us early.
The Fixer-Upper: Purchase Plus Improvements
Found the right house on the right street with the wrong kitchen? A Purchase Plus Improvements mortgage rolls the renovation cost into your mortgage at closing, based on contractor quotes. The renovation funds are released after the work is done and inspected, so you'll need to float the contractor short-term. One mortgage, one payment, the kitchen you actually wanted. The full FAQ is here.
Downsizing
Moving to something smaller often means a mortgage-free purchase or a very small one, but there's still a penalty question on the old mortgage and a strategy question about what to do with the freed-up equity. Downsizing and your mortgage walks through it.
The Process, From Hello to the Next Set of Keys
The steps are the same nine we use for every mortgage. What changes for a move-up buyer is the choreography around them. Here's what's different when you already own a home, and where each piece lands in the order.
1. The 15-minute call: Tell us where you're headed and roughly what your current home is worth. We pull your mortgage details, check your port and penalty rules, and sketch the equity math on the spot.
2. Two approvals, not one: We get you approved with your sale and without it. Now you know which offers you can write today, which ones need a firm sale first, and exactly how much bridge you'd need.
3. Your Strategy Plan: Port, blend or break, side by side, on your numbers. Sell first, buy first or line them up. Every version compared in plain English, and you pick.
4. Rate hold and RateWatch+: Your rate is held for up to 120 days while you list and shop. If your lender's rate drops before closing, we negotiate the lower one for you.
5. List and shop: Your realtor lists; you tour. If you'd like a referral, our partner realtors are used to working move-up timelines with us.
6. Offers, both directions: When your sale goes firm, we flip your approval to the "with sale" version and arrange the bridge if the dates need it. Your purchase offer goes in with a financing condition and a number you can stand behind.
7. The lawyer, once: One real estate lawyer handles both your sale and your purchase, pays out the old mortgage, receives the bridge, and coordinates the funds so the dates work.
8. Fourteen updates: Same as every file. Closing costs spelled out a week ahead so moving week is about boxes, not bank drafts.
9. Keys: Old ones handed in, new ones handed over, playlist on. Then the monthly homeowner reports start again for the new place.
Want the full nine steps with all the personality? Here's how it works.
Guides for Your Next Move
Sell First or Buy First? How to Decide When You Already Own a Home
Every move-up buyer hits the same fork. Here's the honest trade-off, the middle paths most people miss, and the two-approval trick that turns the riddle into five minutes of math...
Learn More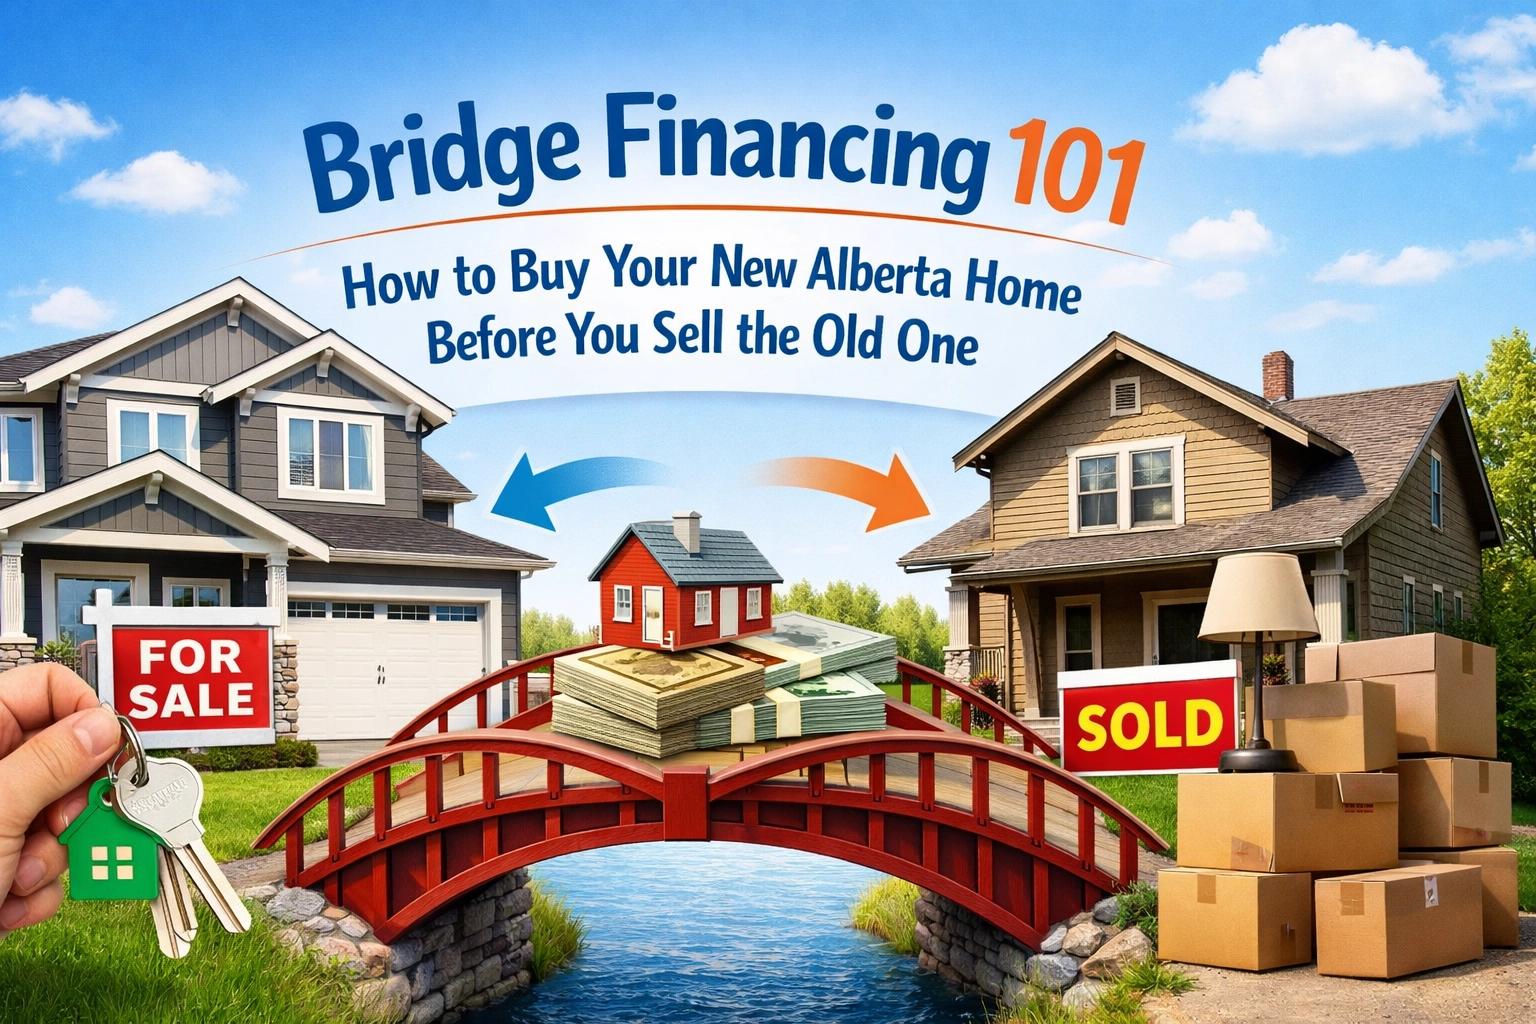
Bridge Financing 101: How to Buy Your New Home Before You Sell the Old One
Need to close on the new place before the old one sells? Bridge financing floats your down payment for the gap. What it costs, what lenders need, and when it's worth it...
Learn More
Porting Your Mortgage: How It Works and When It Beats Paying the Penalty
Take your rate and term to the next house and skip the penalty. The 30-to-120-day window, the blended-rate math, and when breaking is actually the smarter call...
Learn More
Downsizing: What Happens to Your Mortgage When You Move to Something Smaller
A smaller home can mean a smaller mortgage or none at all. What happens to the penalty, the equity and the plan when you move down instead of up...
Learn MoreShort reads from the Strategy Vault — the questions move-up buyers ask us before they list.
Next-home questions
The questions you’re asking. And the ones you should be.
- Should I sell my house first or buy the new one first?
- It depends on the market you're selling into, whether your income can carry two payments for a short stretch, and how much your budget depends on the sale price. In a hot market in Alberta, buying first (with a bridge loan once your sale is firm) is common; in a slower one, selling first with a long possession date is calmer. Most of our clients line the two up with closings a few days apart. We get you approved both ways so you know which offers you can write before you start.
- Can I buy a new home before my current one sells?
- Yes. Until your sale is firm, the lender needs you to qualify carrying both mortgages. Once it's firm (conditions waived), a bridge loan covers your down payment between the two closing dates and is repaid automatically from the sale proceeds.
- What is bridge financing and what does it cost?
- A short-term, interest-only loan that floats your down payment from the day your purchase closes until the day your sale closes. Lenders need firm agreements on both ends. Interest runs at roughly prime plus a few percent for only the days you use it, plus a modest admin fee, so a two-week bridge typically costs hundreds, not thousands.
- Can I port my mortgage to the new house?
- Usually, if it's a fixed rate. Porting moves your rate, term and remaining amortization to the new property with no penalty, as long as you close within your lender's window (typically 30 to 120 days) and requalify. If you need more money, the lender blends your old rate with today's rate on the new portion. Most variable-rate mortgages have to be converted to fixed before they can be ported.
- What's the penalty if I break my mortgage to move?
- Variable rate: almost always three months' interest. Fixed rate: the greater of three months' interest or the Interest Rate Differential, which big banks calculate off posted rates and can push into five figures. If your renewal date is close, timing your closing to it can eliminate the penalty. We request the exact payout figure from your lender before you decide anything.
- How do I know how much equity I have for the down payment?
- Roughly: what the home will sell for, minus your mortgage balance, minus realtor commission, legal fees (about $1,000–$1,500 in Alberta) and any penalty. Our home equity calculator gives you a quick number; your realtor's market evaluation and your lender's payout statement make it exact.
- Do I need 20% down on my next home?
- No. The same minimums apply as any purchase: 5% on the first $500,000 and 10% on the portion above that, up to a $1.5 million price. Under 20% the mortgage is insured and gets the sharpest rates. Twenty percent or more skips the insurance premium and unlocks 30-year amortizations. We compare both on your numbers; the answer isn't always the obvious one.
- Is it harder to qualify the second time?
- Not harder, just more moving parts. If your sale isn't firm yet, the lender counts your current mortgage payment (and any HELOC) as debt. If you're porting, it's a fresh approval on the new property. The stress test still applies at the higher of 5.25% or your rate plus 2%.
- Can I write an offer conditional on selling my home?
- You can, but in a competitive market it's the weakest condition on the table and sellers often pass. Getting approved both with and without your sale lets you know when you can safely drop that condition, and a bridge loan is what makes a firm offer possible before your sale closes.
- How do I line up the closing dates?
- Ideally your sale closes a few days before your purchase, so the proceeds are in your lawyer's trust account when the new mortgage funds. If it has to be the other way around, a bridge covers it. One real estate lawyer handling both transactions keeps the money moving in the right order, and we coordinate the dates with them.
- What about a new build, acreage or condo?
- Each has a wrinkle. New builds need a rate hold long enough to survive the build and your own lawyer, not the builder's. Acreages get valued on the house plus limited land, with wells and septic inspected. Condos add part of the fee to your qualifying debts and require a document review. Tell us the property type early and we match you to a lender that's comfortable with it.
- What does this cost me?
- On the vast majority of purchases, nothing. The lender pays our fee when the mortgage funds. Your own costs are the usual ones: legal fees, Land Titles registration (Alberta has no land transfer tax), the appraisal if the lender needs one, and any bridge interest or penalty, all spelled out a week before closing.