Two houses, two cities, two years
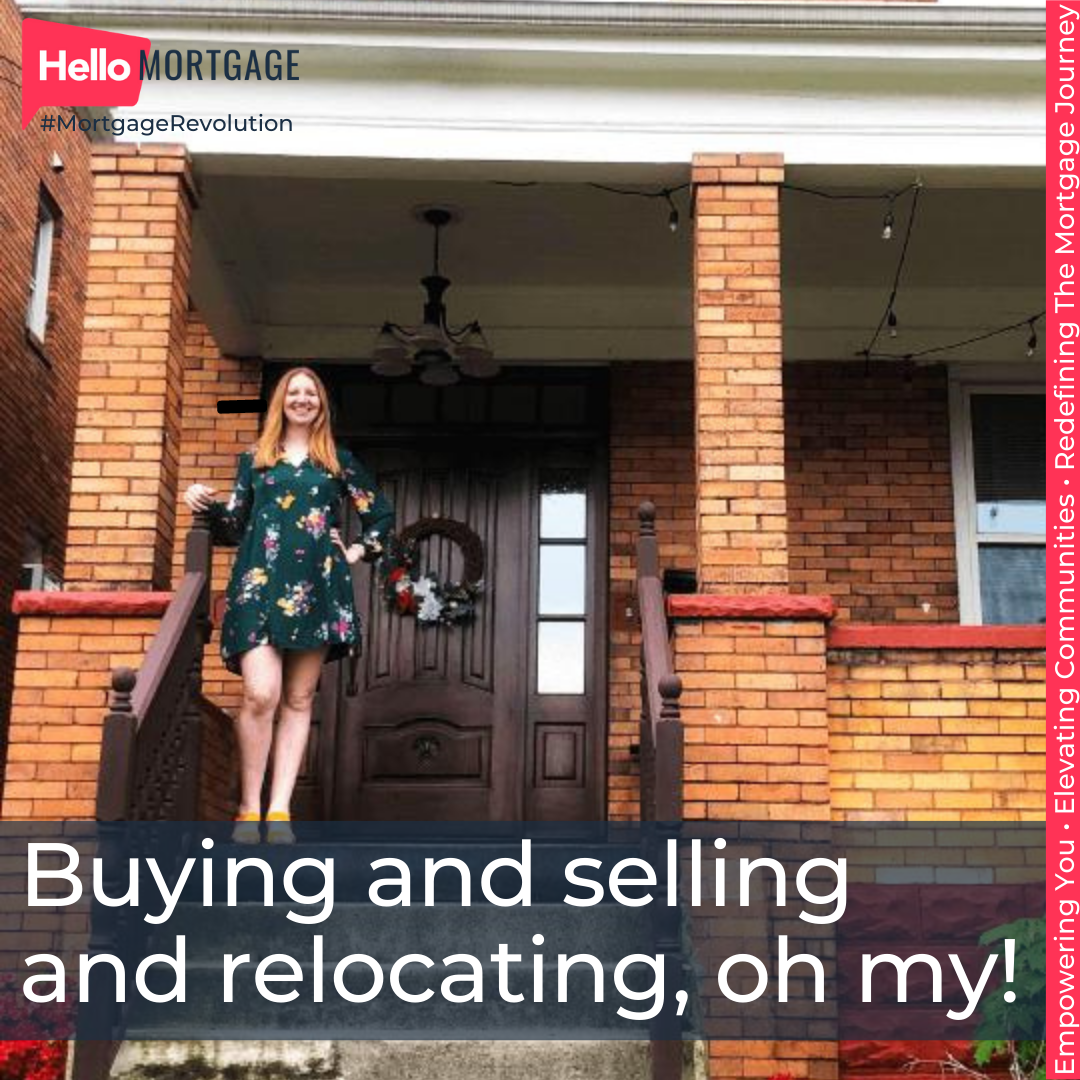
Amy bought her first house in Red Deer at 23. Two years later, she sold it and moved to Calgary. She's 25 now, owns her second home, and didn't have to choose between mobility and homeownership.
The key? Mortgage insurance let her buy her second home with less than 20% down — which meant she could keep most of her sale proceeds in the bank instead of tying them all up in a new down payment.
Why she moved
Amy loved her first little house in Red Deer and made lots of friends there. But a job opportunity came up that was too good to pass up. She's now a regional sales manager for a major coffee company in Calgary.
Before the move, she went through the ups and downs of buying and selling houses in two different cities.
Selling her first home in Red Deer
Red Deer had a shortage of homes for sale and a lot of buyers when Amy listed. She didn't have time to make any major improvements to her 1904-built house, but she added a simple deck, lots of flowers, and new bushes. "It has more curb appeal than when I bought it," she said.
The hardest part? Keeping it clean all the time and ready for prospective buyers to tour.
Amy sold her house for $361,000 — $21,000 more than she paid in 2017. Even in that short time, she'd accumulated some equity. When the sale closed, she walked away with $28,000.
Buying her second home in Calgary
Next step: find a house in Calgary. Home prices are higher there than in Red Deer, and this time Amy wanted to buy something nicer and more expensive.
"I found one that was a little bit above my price range at $400,000. But it's in perfect condition — I don't have to worry about repairs or anything," she said. Coffee shops and restaurants are within walking distance.
As a single person who works long hours, finding a low-maintenance home was important. But she also wanted to keep some money in the bank, just in case.
Why she chose mortgage insurance again
Amy could have used all $28,000 from her Red Deer sale as her down payment. But she didn't want to drain her savings account.
She used mortgage insurance (also called a high-ratio mortgage — it's what lets you buy with less than 20% down) again, so she could put down just 5%: $20,000. "My monthly payment is a little bit higher but still affordable. Thanks to mortgage insurance, I could buy a better house and still have money in the bank."
If you're relocating and want to keep some liquidity without waiting years to save a full 20% down, mortgage insurance can make the numbers work. It's worth running the scenarios before you assume you need to empty your accounts.