Your new house will surprise you
No matter how thorough your home inspection is, odds are your new house will reveal a surprise shortly after you move in — and it won't be the housewarming party.
Why one buyer put down less than she could
That's why Andrea was prepared the second time she bought a house. Andrea is a digital marketing manager who relocated to Edmonton from Toronto. She had enough saved from the sale of her home for a 20% down payment, but she chose 10% and financed with mortgage insurance instead.
She explained: 'I wanted to have some cash on hand for unexpected expenses. After all, if I wanted to, I could always pay down the principal on my mortgage later with that cash.'
The surprise: a completely bare yard
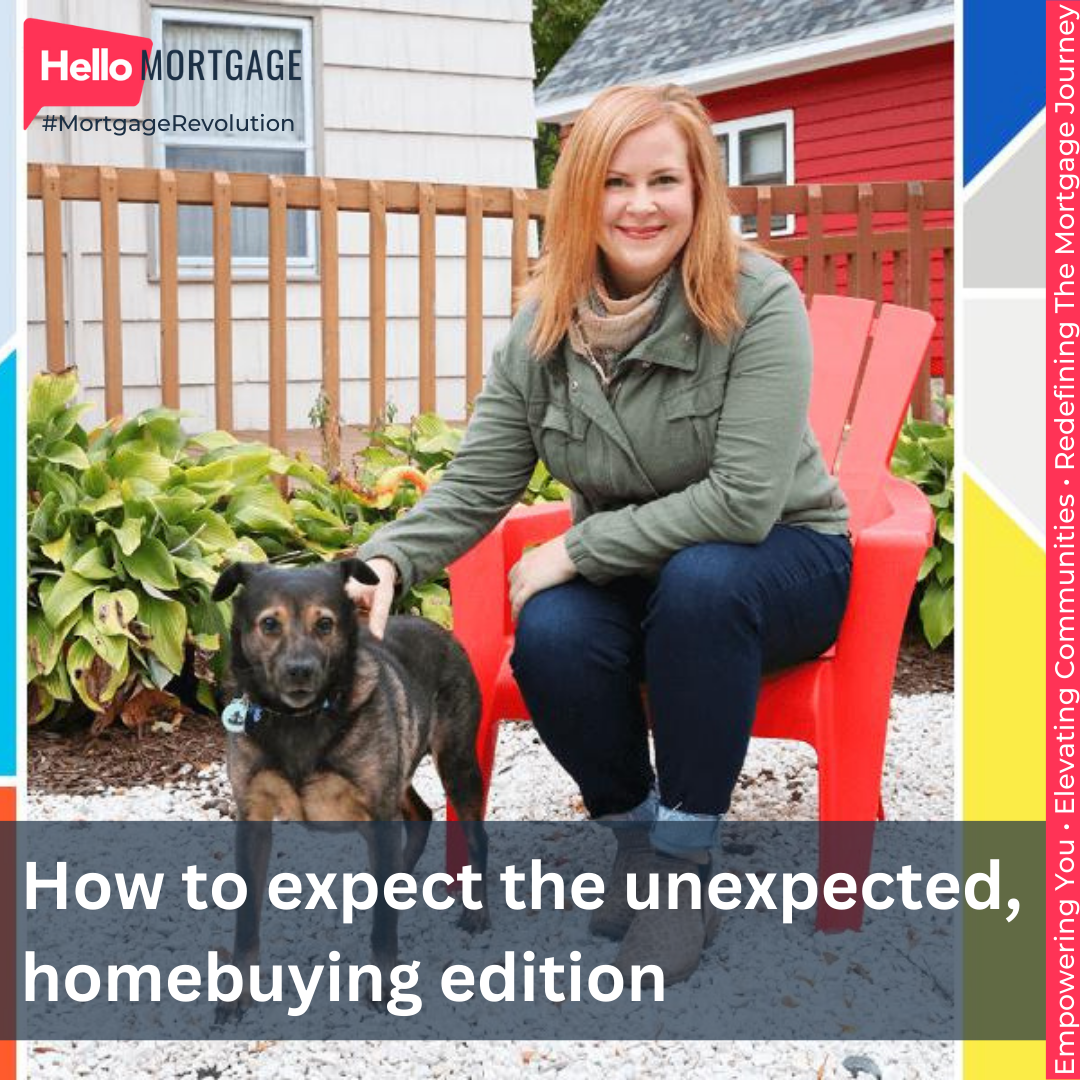
The inevitable 'unexpected expense' was a surprising one. Andrea closed on her house in March, and when the snow melted later that spring, it revealed a yard completely bare of landscaping. 'It never occurred to me to ask for photos of the house from another season!' she noted.
Consequently, Andrea used some of her cash for a retaining wall, bushes, flowers, patio pavers, gravel and a fire pit. 'It was a blessing in disguise,' she said. 'Building it up from nothing gave me the chance to make the outdoor space completely my own and perfect for my two older dogs.'
A revolving line of renovation credit
Renovations were the main reason she wanted to make a smaller down payment. She was excited to put her own stamp on the house and had always wanted to explore DIY projects. It took her five months to find the 1950s ranch home of her dreams in Laurier Heights. 'It's a fixer-upper, but I am using that chunk of savings as my own revolving line of home renovation credit,' she said.
Right after closing, some of those funds went toward common expenses new homeowners face, like lawn-care equipment. Then she replaced all the carpet, tore out a partial wall in the kitchen that was blocking full use of her French doors and replaced the ugly painted-over tile backsplash. She hired experts when necessary, but did as much as possible herself to maximize her budget.
What you can take from this
For Andrea, there's always another project on the horizon. She enjoys the process as much as the results. And she's thankful a smaller down payment gave her those renovation options.
If you're buying your first home — or your next one — think about what cash in hand is worth to you after closing. A bigger down payment shrinks your mortgage, but it also shrinks your options when the yard turns out to be gravel or the kitchen needs work. You can always throw extra money at the mortgage later. You can't always pull it back out when you need it.



