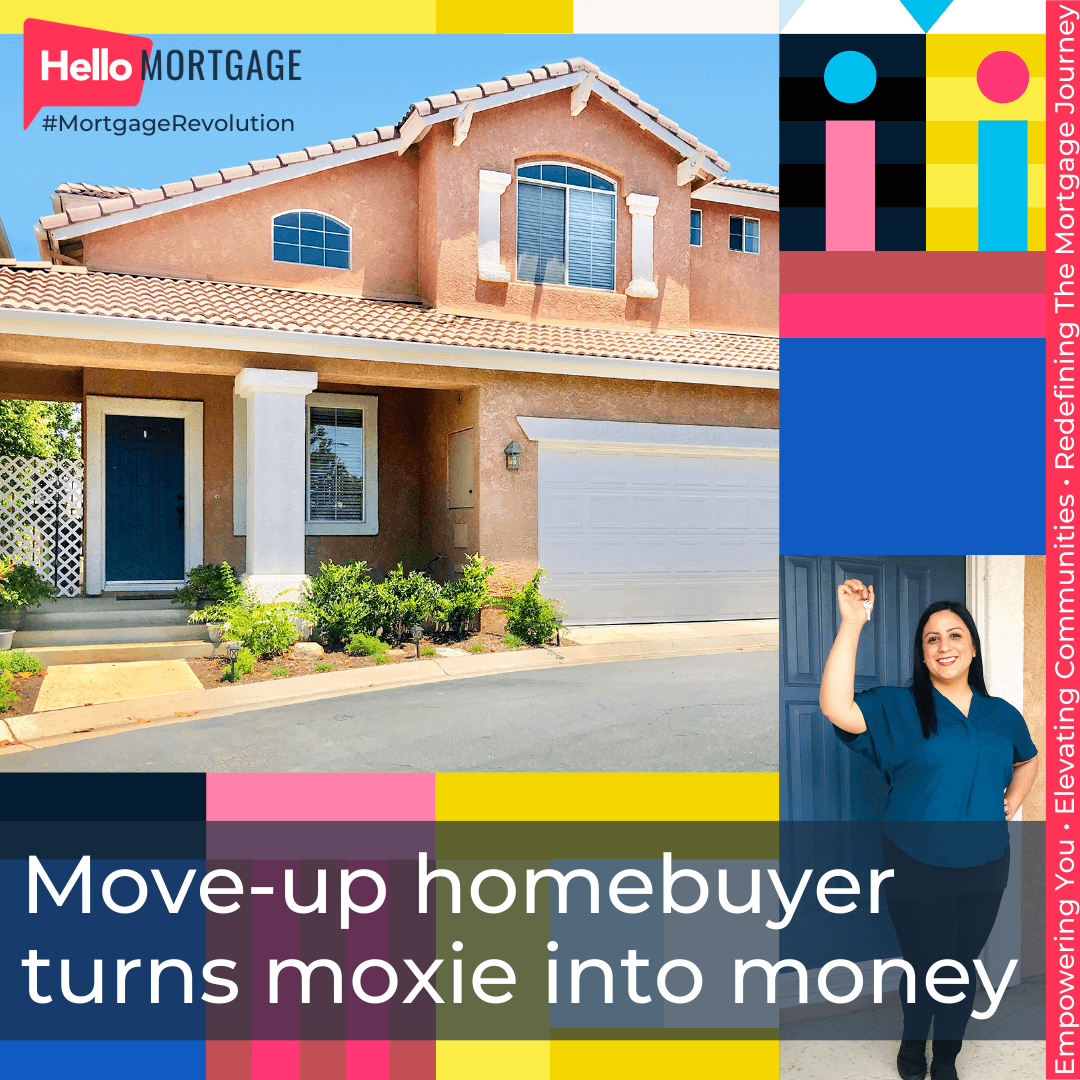
Becoming a homeowner sooner
Three years ago, Jocelyn was 28, single, and determined to own a home before 30. She wasn't going to wait until she had 20% saved.
Her parents thought she should hold off for a bigger down payment. Jocelyn had other plans.
"I did my homework and knew mortgage insurance would let me put down as little as 5%," she says. "I bought my townhouse for $278,000 and put down $13,900. It would have taken me almost 8 years to save $55,600 for a 20% down payment. As it was, my 5% down payment used up most of my savings."
Mortgage insurance (often called CMHC insurance, though other insurers exist) lets you buy with less than 20% down. You pay a premium — added to your mortgage — but you get in the door years earlier.
Taking advantage of an equity boost
Fast forward a few years and her decision paid off. Low rates and strong demand pushed her home's value up. In March 2021, she sold her townhouse and walked away with an $86,926 profit.
"Imagine if I had waited 8 years to save for a 20% down payment!" she says. "I wouldn't have been able to get my foot in the door when I did."
Using her profit wisely when buying her next home
The sale let Jocelyn move up to a much larger house in a gated community. Most move-up buyers at this stage put down 20% or more from their sale profit.
Jocelyn went a different route. She bought her second home for $537,500 and put down 11% — $60,000 — even though she had enough for 20%.
"In my last house, I cut myself short by using almost all my savings for the down payment," she explains. "I didn't want to do that this time. I knew my new house needed some repairs and updates. Plus, I was buying during the pandemic, and I wanted ready cash in case I lost my job."
Her choice gave her the financial freedom to remodel her kitchen, buy furniture, pay off two credit cards, and still have savings left for a rainy day.
Another equity boost
On top of having a bigger house in a better location, Jocelyn reports that four homes like hers in the neighbourhood sold in the $550,000 to $560,000 range — likely adding $17,500 to her equity in less than six months.
"I try to educate people about all the tools and resources available," she says. "I tell them, 'I'm living proof.' Had I waited those 8 years to save for a 20% down payment, I would have missed out on all this money and the perks of being a homeowner."
If you're debating whether to wait or buy with mortgage insurance, run the numbers with your broker. Sometimes the cost of waiting — in appreciation you miss and rent you keep paying — outweighs the insurance premium. Sometimes it doesn't. Your call, your timeline, your strategy.



